Can Chapter 13 Bankruptcy Help Stop Foreclosure and Protect Your Home in Illinois?
Quick Summary:
If you are behind on mortgage payments or facing foreclosure in Will County, Chapter 13 bankruptcy may provide a structured way to address past-due payments while you work to keep up with future obligations. Filing can trigger important court protections and may allow mortgage arrears to be paid over time through a repayment plan. It is not a guaranteed solution, however, and the right option depends on your income, the stage of foreclosure, your mortgage terms, and your full financial picture.
Falling behind on a mortgage can feel deeply personal, especially when the home holds your family’s routines, memories, and plans for the future. If you are receiving notices from your lender or have learned that a foreclosure case has been filed, you still deserve clear information and a calm conversation about your options.
For some homeowners, a Chapter 13 case can be part of a plan to stop foreclosure through bankruptcy in Illinois. The bankruptcy services
team at the Law Office of Sara J. Gray, P.C. helps families in Joliet and throughout Will County review the facts carefully and understand what may be realistic in their circumstances.
What Chapter 13 Is Designed to Do
Chapter 13 is often called a repayment or reorganization bankruptcy. Instead of trying to resolve every debt at once, it generally creates a court-supervised repayment plan that lasts three to five years. The plan is built around household income, necessary expenses, debts, and property.
For a homeowner who is behind on a mortgage, the past-due amount is often called the mortgage arrears. Depending on the facts of the case and court approval, a Chapter 13 plan may allow those arrears to be paid over the life of the plan rather than in one large payment.
This is why people searching for ways to stop foreclosure with Chapter 13 in Illinois
often consider this chapter. The goal is not simply to delay a difficult decision. It is to determine whether a workable budget and repayment plan can support the household going forward.
How Filing May Affect a Foreclosure Case
When a bankruptcy case is filed, an automatic stay generally takes effect. In plain language, it is a court protection that usually pauses many collection efforts, including a pending foreclosure, unless the bankruptcy court allows the lender to proceed.
That pause can create room to submit a Chapter 13 plan and address the financial issues that led to the missed payments. It does not erase the mortgage or permanently prevent foreclosure in every situation. A lender may ask the court for permission to continue the foreclosure, and the homeowner must meet the obligations required by the case.
Because the automatic stay is only one part of the larger process, this article focuses on the broader decision: whether Chapter 13 offers a realistic path for your home, income, and budget. A Joliet bankruptcy lawyer
can explain how the protections and responsibilities may apply to your individual situation.
Why Timing Matters in Illinois Foreclosure
Illinois uses a judicial foreclosure process, meaning the lender generally must proceed through court before a home is sold. That process can involve multiple notices, filings, deadlines, and hearings. The amount of available time varies from case to case.
Speaking with a Chapter 13 attorney in Will County early gives you more time to gather pay records, mortgage statements, tax returns, a list of household expenses, and foreclosure paperwork. It also allows more time to assess options outside bankruptcy, such as a lender workout, modification, sale, or other resolution when appropriate.
Even if a sheriff’s sale has been scheduled, it is worth getting direct advice about your specific timeline. Important legal rights and practical options can change as a foreclosure case moves forward. Waiting can limit choices, but panic does not help. A prompt, informed review is the better next step.
Mortgage Payments Do Not Usually Disappear
A Chapter 13 plan may address missed payments from before filing, but homeowners generally must also plan for ongoing mortgage obligations that come due after filing. Depending on the mortgage and the plan, that can include regular monthly mortgage payments, property taxes, homeowners insurance, and other escrowed costs.
This distinction matters. A repayment plan must be feasible, not merely hopeful. If the household budget cannot support the regular mortgage payment plus the proposed plan payment, Chapter 13 may not be the right answer without another change in circumstances.
Homeowners should also understand that missed post-filing payments can create serious problems in a Chapter 13 case. Honest budgeting and complete information are essential to evaluating whether you may be able to save a home from foreclosure in Illinois.
Income and a Workable Household Budget
Steady income is important in Chapter 13 because the plan requires regular payments. Income can come from employment, self-employment, retirement, disability benefits, or other sources, depending on the circumstances. The question is not simply whether you have a job. It is whether there is enough reliable income, after reasonable living expenses, to support the proposed plan.
A bankruptcy attorney in Will County can help review the complete picture: income, household size, mortgage arrears, vehicle payments, tax obligations, credit cards, medical bills, and other debts. The Law Office of Sara J. Gray, P.C. believes clients deserve straightforward explanations rather than assumptions about what they can afford.
When Chapter 13 May Not Be the Best Fit
Chapter 13 is not guaranteed to stop a foreclosure permanently or allow every homeowner to keep a house. A plan may not be feasible if income is too limited, the arrears are too large for the available budget, post-filing payments cannot be maintained, or other legal and financial factors apply.
In some situations, a loan modification, negotiated sale, or another strategy may deserve consideration. For others, comparing Chapter 7 and Chapter 13 bankruptcy in Illinois may be appropriate. The best choice is personal. It should be based on accurate documents, realistic monthly numbers, and a conversation about your priorities.
Helpful Documents to Gather Before You Call
You do not need to solve everything before speaking with an attorney. Still, having a few documents available can make the first conversation more productive:
- Your most recent mortgage statement and any default or foreclosure notices
- Foreclosure court papers and the date of any scheduled sheriff’s sale
- Recent pay stubs or other proof of household income
- Recent bank statements and tax returns, if available
- A simple list of regular monthly household expenses and other debts
These records help a Chapter 13 attorney in Will County identify questions that need answers and discuss whether a repayment plan could be realistic.
FAQ
Can I keep my house if I file Chapter 13 in Illinois?
Possibly. Chapter 13 may offer a way to address mortgage arrears over time, but keeping a home depends on the specific facts, including your budget, income, mortgage status, property obligations, and ability to make required payments.
Can Chapter 13 stop a foreclosure in Will County?
Filing may trigger the automatic stay, which generally pauses a pending foreclosure at first. However, the lender can seek court permission to continue, and the case must meet all bankruptcy requirements. It is not a promise that foreclosure will be permanently stopped.
What if a sheriff’s sale has already been scheduled?
Speak with an attorney as soon as possible. The timing and available options depend on the status of the foreclosure case and other facts. Do not assume that a scheduled sale answers every legal question, but do not delay getting individualized guidance.
Do I need a certain income to file Chapter 13?
Chapter 13 generally requires regular income sufficient to support a feasible repayment plan. The source and consistency of income, necessary living expenses, and the amount of debt all matter.
Do I still have to pay my current mortgage during Chapter 13?
In many cases, yes. A Chapter 13 plan may address the past-due amount, while regular ongoing mortgage payments and related property costs remain due. The details depend on the proposed plan and your mortgage.
Why should I speak with a bankruptcy attorney before deciding?
Foreclosure and bankruptcy involve deadlines, paperwork, and choices that are difficult to evaluate from a general article. A conversation with an attorney can help you understand your timeline, your obligations, and whether Chapter 13 or another path fits your goals.
Talk Through Your Next Step With Personal Attention
This article is general information only and is not legal advice. Every foreclosure and bankruptcy situation is different, and reading this post does not create an attorney-client relationship.
If you are behind on mortgage payments in Joliet, Plainfield, Bolingbrook, Romeoville, New Lenox, Lockport, or elsewhere in Will County, the Law Office of Sara J. Gray, P.C. is ready to provide quick, direct answers without judgment. Our small firm offers personal attention, bilingual English and Spanish staff, and reasonable fees for people already under financial strain. Visit our bankruptcy page, learn more about our Joliet law office, or contact us to discuss your situation. We are a debt relief agency. We help people file for bankruptcy relief under the Bankruptcy Code.
About The Author
Sara J. Gray | Attorney
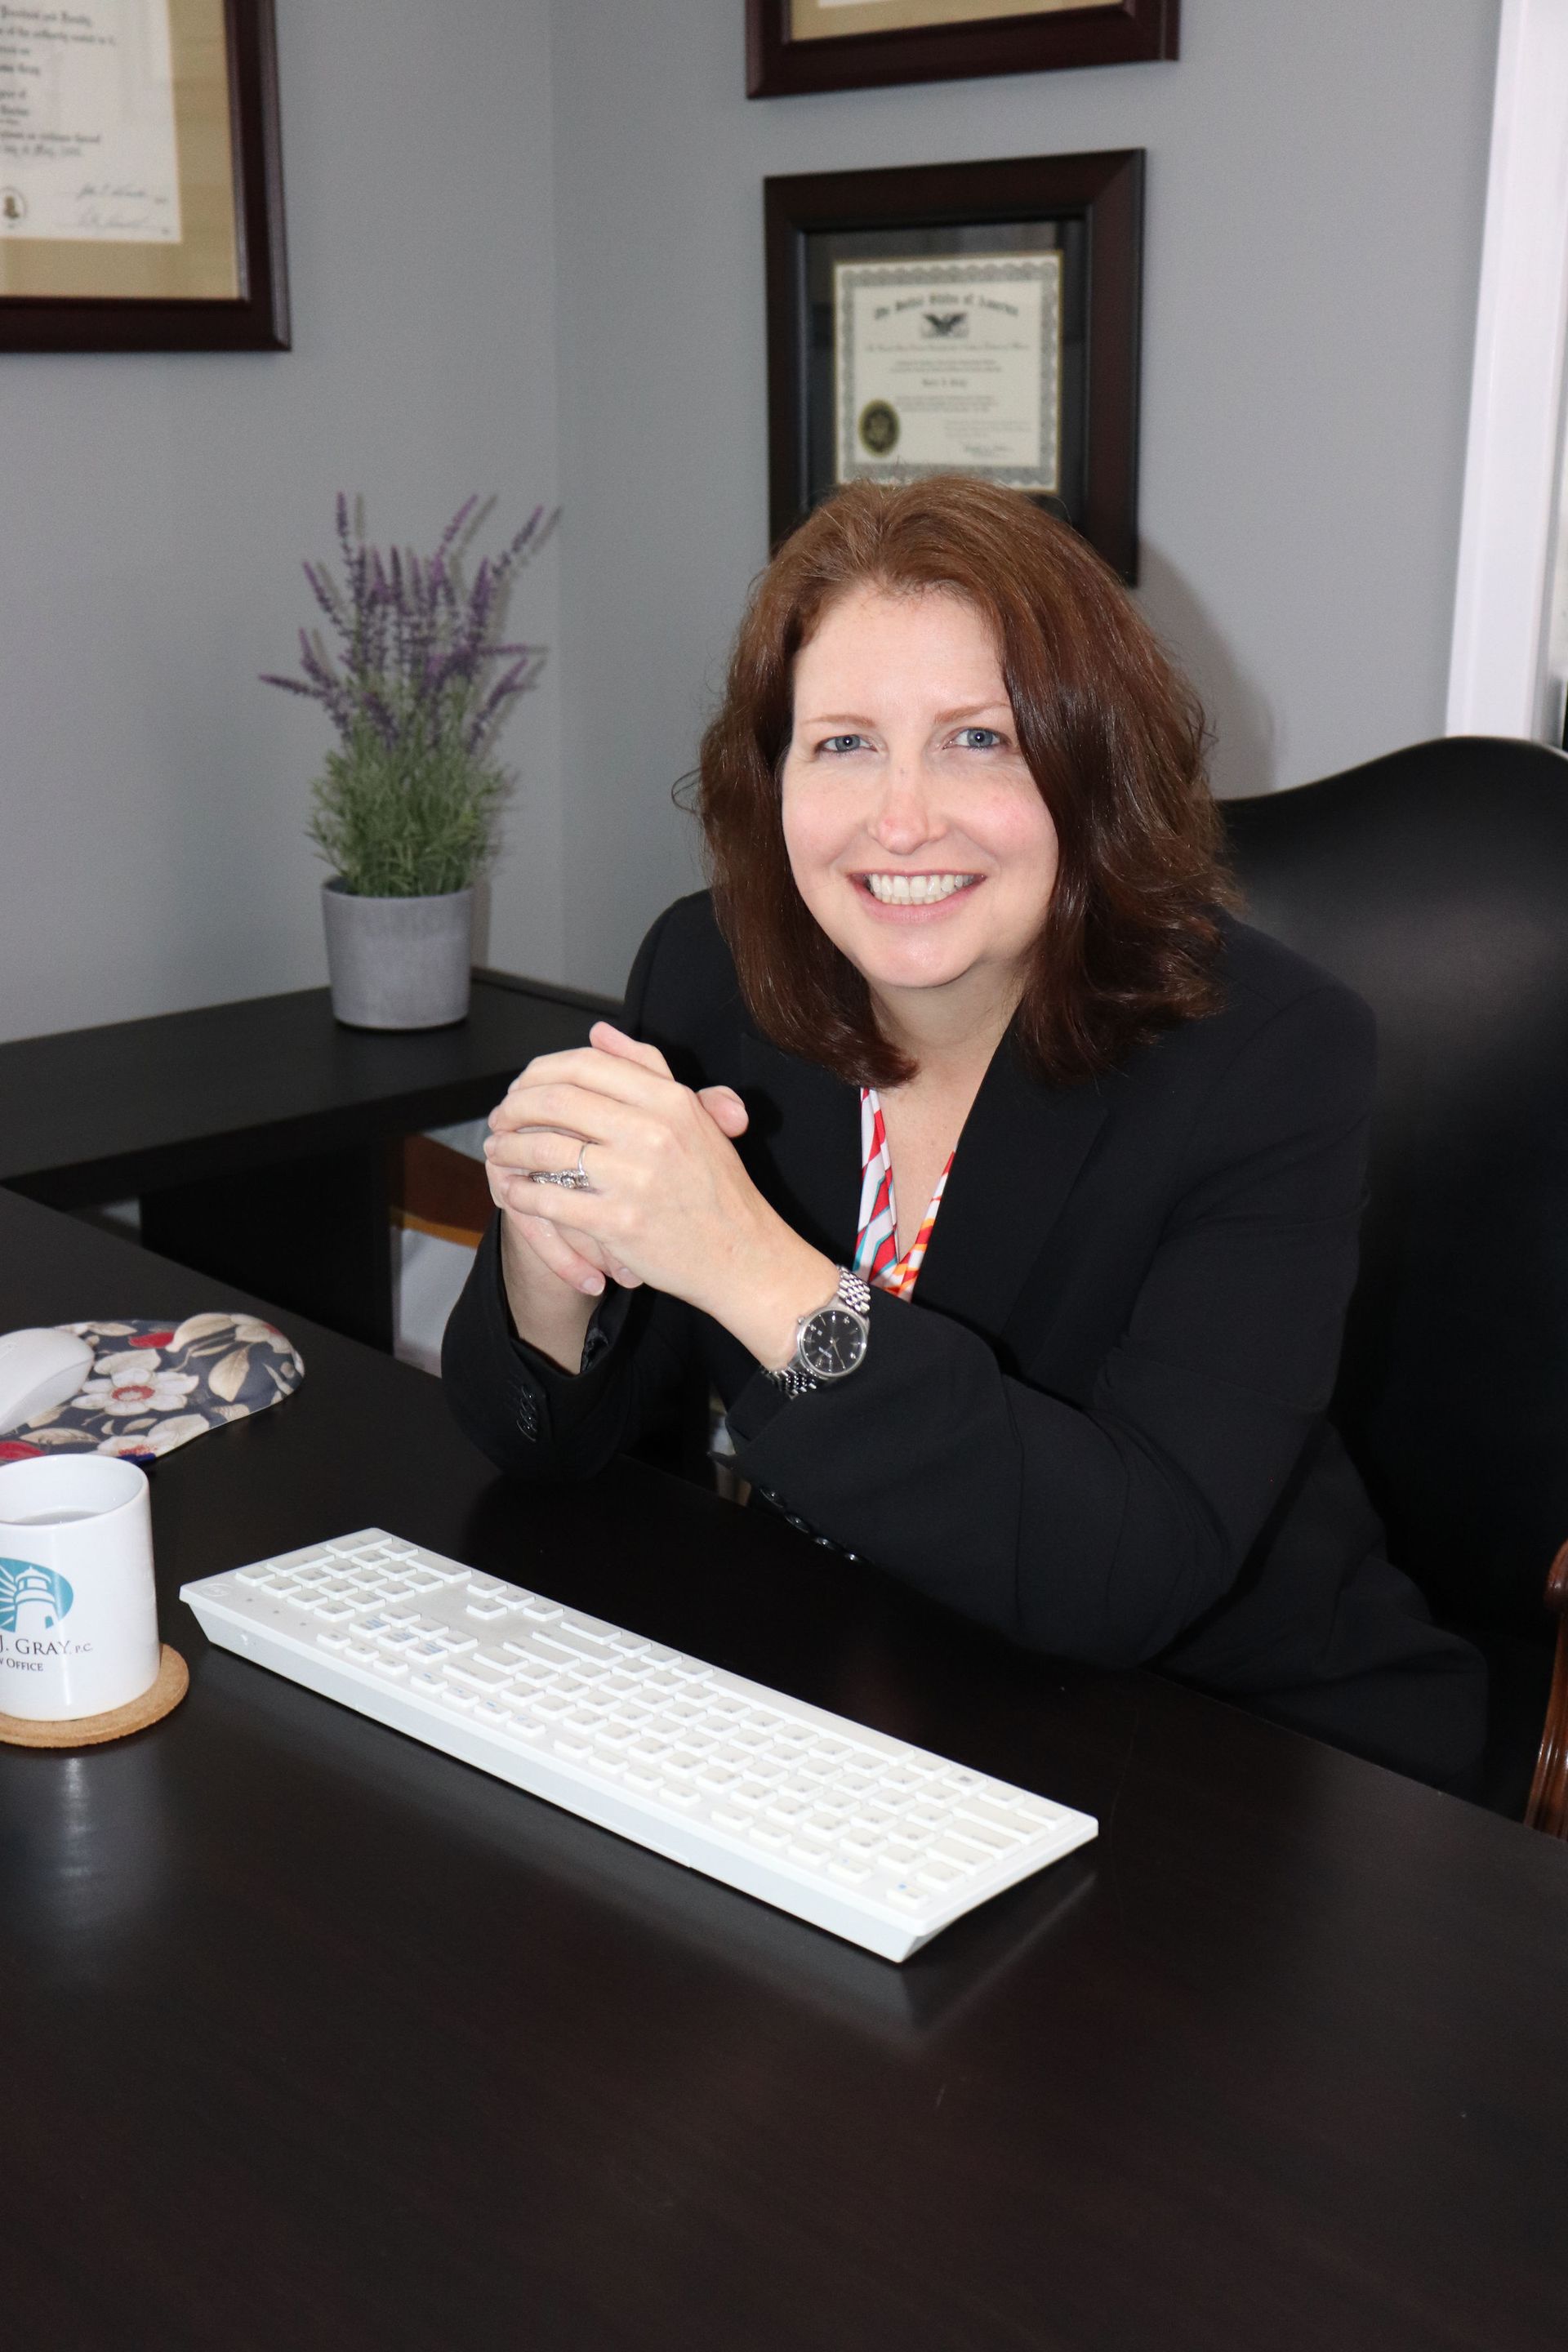
Sara J. Gray is the founder and principal attorney of the Law Office of Sara J. Gray, P.C., a general practice law firm in Joliet, Illinois serving Will, Kendall, Grundy, Cook, and DuPage counties since 2001. With 25 years of experience and more than 1,000 bankruptcy cases filed, Sara focuses her practice on helping individuals and families find real solutions to financial hardship, real estate transactions, and criminal or traffic charges — without the runaround, the inflated fees, or the revolving door of attorneys that larger volume firms are known for. Her office is fully bilingual in English and Spanish, and Sara and her staff take pride in making the legal process approachable for clients who may be walking through a law office door for the first time. When she's not in court or at the closing table, Sara is most likely at her Joliet office on Plainfield Road — same place she's been for over two decades.